Dividend Reinvestment Plans: When to Reinvest or Take Cash
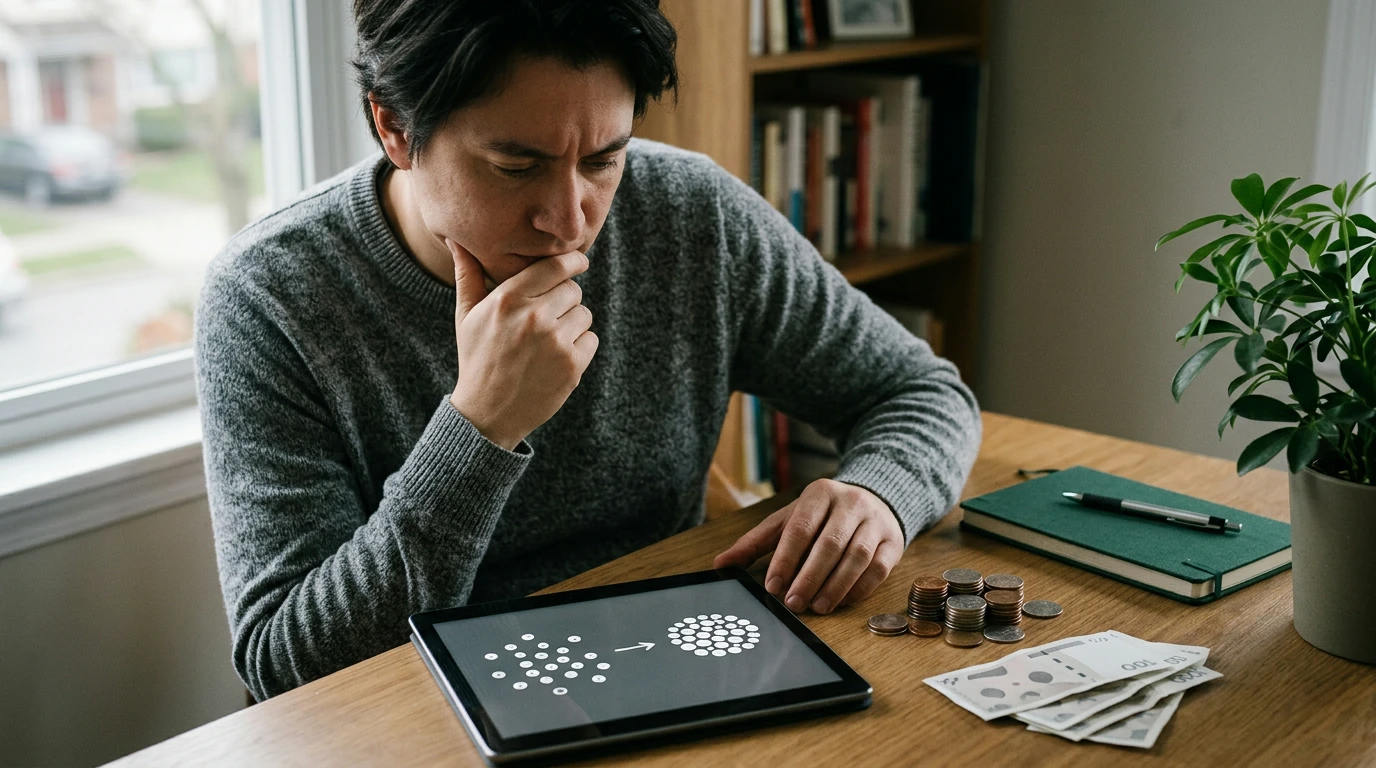
When an investment pays a dividend, you can usually take the payment in cash or, if your investment and account are eligible, use it to buy more shares. A dividend reinvestment plan, or DRIP, automates the second choice. It can be a practical way to keep money invested, but it is not a shortcut to guaranteed growth or spendable income. The useful question is whether reinvesting fits what you need the dividend to do.
How a DRIP works
The sequence is straightforward: an investment pays a dividend, the payment goes toward additional shares, and those shares may receive future dividends. Suppose you own shares that pay you a $20 dividend. If reinvestment is available and a share costs $50 at the purchase price, a plan that permits fractional shares could buy 0.4 share with that payment. The example shows the mechanics, not a projected return. Future dividends and share prices could be higher or lower.
There are two common ways to arrange reinvestment. A company-sponsored DRIP is administered for eligible shares under that company’s plan rules. A brokerage may instead offer dividend reinvestment within your account. The distinction matters: eligible investments, fractional-share purchases, fees, and the date and price of a purchase can differ. Before turning on an automatic setting, find out which rules apply to your holding. For a basic definition of the arrangement, see Investor.gov’s explanation of dividend reinvestment plans.
Reinvesting or taking cash: which fits your goal?
Reinvesting makes the most sense to consider when you intend to leave the dividend invested. It buys additional exposure to the same holding rather than providing money you can spend today. If you need current income, are building cash reserves, or want to choose a different investment, taking the dividend in cash may better serve you.
| Consideration | Reinvest the dividend | Take the dividend in cash |
|---|---|---|
| Immediate access | Money goes toward additional shares | Money is available to spend, save, or invest elsewhere |
| Potential long-term effect | Additional shares may generate future dividends | No additional shares are purchased automatically |
| Main trade-off | More money stays exposed to the investment’s price changes | You must make a separate decision if you want to keep investing |
| Best question to ask | Can this money remain invested? | Do I need this income or want more flexibility? |
A DRIP changes what happens after a dividend is paid; it does not make the underlying stock or fund safer. If its price declines, the shares you purchased through reinvestment can lose value along with the shares you already owned. You can also use cash dividends to rebalance among holdings rather than automatically adding to the one that made the payment. Neither choice is universally better—the right setting depends on the job you want that money to do.
The details worth checking before you enroll
First, confirm that both the investment and your account qualify for reinvestment. Ask whether the arrangement buys fractional shares, how any unused dividend amount is handled, and whether purchases or later sales carry fees. Review when your election takes effect, especially if a dividend payment is approaching. Small differences in plan rules can change how closely the result matches what you expect.
Next, look at your whole portfolio. Automatically buying more of one holding can increase your reliance on that company or fund. This may be an acceptable choice, but it should be deliberate. Dividends can be reduced or stopped, and share prices can rise or fall; neither a payment nor an investment gain is guaranteed.
Finally, keep records. In a taxable account, a dividend may still be taxable even when it is automatically reinvested and you receive no spendable cash. Reinvested amounts generally affect your cost basis, which can matter when you sell. Account type and individual circumstances affect tax treatment, so confirm the rules that apply to you. IRS Publication 550 is a starting point for U.S. investment-income and basis rules.
Build a routine around the decision
Start by naming your goal: current cash flow, long-term investment, or flexibility to allocate dividends elsewhere. Then compare the reinvestment options available for your holdings, including their rules and costs. Choose a cash or reinvestment setting, record the choice, and revisit it periodically or when your income needs, portfolio, or time horizon changes. An automatic election can save you a recurring task, but it should not replace an occasional review.
If you want a dedicated resource while you learn about the topic, explore our Dividend Reinvestment Plans (DRIPs) eBook – Unlock Passive Income and Grow Your Wealth. Treat the title as a learning invitation, not a promise that reinvesting will produce passive income you can spend or a particular financial result. For a broader look at everyday financial decisions alongside your investing plans, our Gen Z Smart Money Habits Bundle is another available resource.
Our team encourages you to make the dividend choice that fits your cash-flow needs, risk tolerance, and time horizon. Whether you reinvest or take cash, knowing why you chose that setting makes it easier to recognize when it is time to change it.
FAQ
Do DRIPs guarantee passive income?
No. A DRIP puts dividends toward more shares rather than paying them out as spendable cash. Dividends can also be reduced or stopped.
Do I owe tax on dividends that are automatically reinvested?
Reinvested dividends may be taxable in a taxable account even when you receive no cash. Tax treatment depends on your account and individual circumstances.
Can I stop reinvesting dividends?
Many plans and brokerages allow you to change your dividend election. Their procedures and the date a change takes effect vary, so review your provider’s rules.

Leave a comment